
Match the Corporation Tax group relief claim to the surrender notice
The claimant's return, the surrendering company's return and the consent notice should all show one quantified amount for the claimant's and surrenderer's respective accounting periods. Where a hypothetical S Ltd has £45,000 of current-period trading losses and C Ltd has £28,000 of available total profits, that amount is £28,000 on every document.
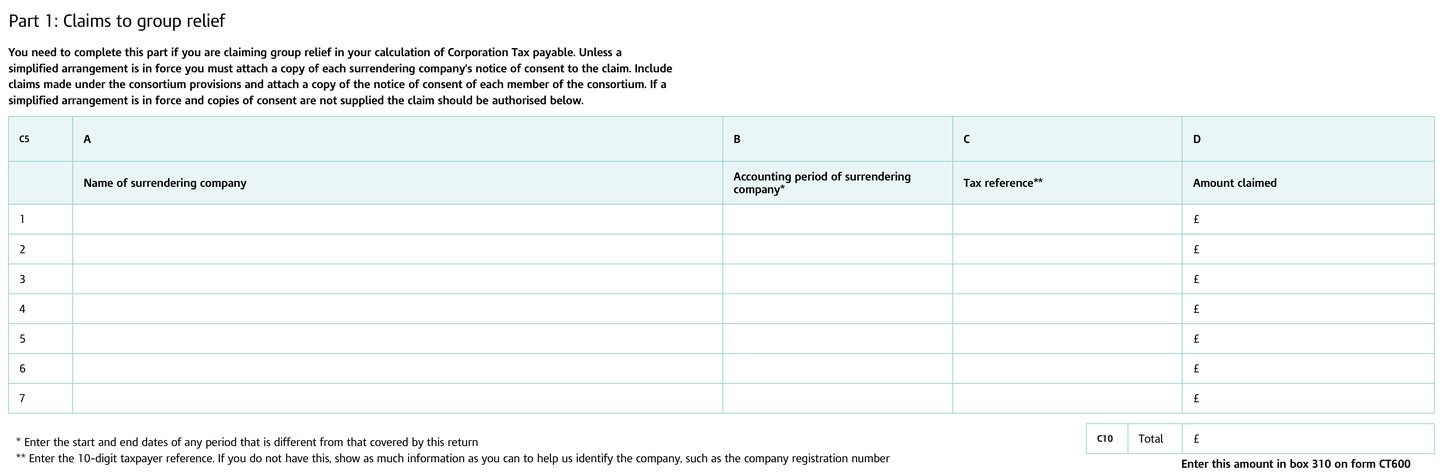
Hypothetical claim for one shared period
S Ltd and C Ltd are qualifying UK group members with the same 12-month accounting period, meeting the group condition throughout. S Ltd has £45,000 of eligible current-period trading losses. C Ltd has £28,000 of available total profits. There are no earlier surrenders or competing claims.
Relief is capped at the lower of the unused surrenderable amount and the claimant's unrelieved available total profits for the overlapping period, so S Ltd consents to surrender £28,000. The other £17,000 is not surrendered here, and this example makes no claim about other relief or cash tax savings. Separate allocation rules apply where periods or group membership do not fully coincide.
Sources and context, checked :
Where £28,000 appears
Part 1 lists each surrendering company, the period where different, its reference and the amount. Parts 3 and 4 cover carried-forward losses and stay blank here. An authorised person can complete Part 2 as the notice if the surrendering company's details are included.
| Return | Entry | Amount |
|---|---|---|
| C Ltd CT600C Part 1 | S Ltd details, amount in C5 | £28,000 |
| C Ltd CT600C | C10 | £28,000 |
| C Ltd CT600 | Box 310, from C10 | £28,000 |
| S Ltd CT600C Part 2 | Current-period trading losses surrendered | £28,000 |
Sources and context, checked :
What the consent and claim must show
An ordinary consent identifies both companies, both tax-office references, the amount and the surrendering accounting period. Unless a simplified arrangement applies, give consent at or before the claim and attach the copy. If S Ltd had already filed, it would amend its return when giving consent.
The claim must be quantified and made in a return or amended return. It can be withdrawn and replaced, not simply varied. Each surrendering company and each accounting period needs its own claim. The deadline generally runs to the first anniversary of the statutory filing date for the claimant's return, with extensions in certain cases.
Before filing
A common owner or associated-company status alone does not establish Part 5 group eligibility. Consortium, carried-forward and cross-border cases fall outside this workflow. Keep the following in the claim file.
Put the C5, C10, box 310 and Part 2 figures side by side with the notice. Reconcile the figures and secure the consent before filing the claimant's return.
- The group relationship and overlapping-period check
- Loss available and claimant capacity after other relief
- The signed or otherwise duly authorised notice
- Both return copies or amendments, with evidence of timing
Sources and context, checked :