
Company trading losses: map the previous 12 months before claiming
A company changed its year end and then made a £30,000 tax trading loss in the year to 30 June 2026. Its two previous returns show £46,600 of profit, which looks like plenty of room. Ordinary carryback is narrower. After current-period profits are relieved, it reaches only the 12 months ending immediately before the loss period starts, and on these hypothetical figures that allows £28,400.
Fix the tax loss and use current profits first
HMRC's guidance starts a tax trading loss with the result in the accounts, then applies tax adjustments such as capital allowances and balancing charges. The accounting loss is not automatically the amount you claim.
HMRC's manual on relief against total profits sets the order. The company cannot carry a loss back without first using it against total profits of the loss period. If it claims carryback, it must then use as much as possible against the previous 12 months, up to the available losses or profits. Relief runs against total profits, so chargeable gains are included.
This is the ordinary rule. The extended three-year carryback from the COVID period covered accounting periods ending from 1 April 2020 to 31 March 2022, and terminal loss relief is a separate claim.
Draw the window from the loss period's start date
The window is the 12 months ending immediately before the first day of the loss-making accounting period. HMRC's manual on preceding periods adds three points. The company must have carried on the same trade at some time in each earlier accounting period it uses. Where an earlier period straddles the window, profits are apportioned. The most recent periods go first.
Our hypothetical company has an ordinary continuing UK trade and no current-period other profits, group, ownership change, special restriction, terminal loss or other claims. Its loss period runs from 1 July 2025 to 30 June 2026, so the window runs from 1 July 2024 to 30 June 2025. Time apportionment uses actual days.
The 184 days from 1 July to 31 December 2024 fall inside the window, so £36,600 x 184/366 gives £18,400. The other £18,200 of 2024 profit sits outside it. The carryback is £10,000 + £18,400 = £28,400, and £1,600 of the loss remains for potential future relief.
| Earlier period | Total profits | Inside the window | Loss relieved | Loss left |
|---|---|---|---|---|
| 1 January to 30 June 2025 | £10,000 | All of it | £10,000 | £20,000 |
| Calendar year 2024 | £36,600 | 184 of 366 days | £18,400 | £1,600 |
Sources and context, checked :
Make the claim and recalculate the earlier tax
HMRC's guidance says to claim normally within 2 years of the end of the loss period, which points to 30 June 2028 in this example. The claim can go in the return, in a permitted amendment or in a letter giving the company, the loss period, the amount and the proposed use.
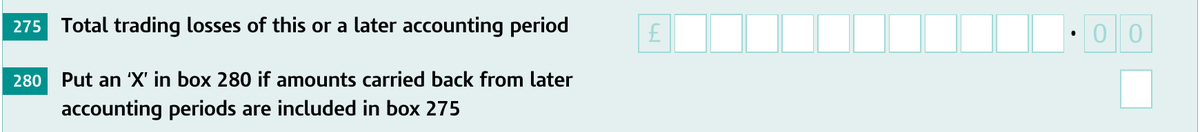
The CT600 guide says the loss-period return must have been delivered before a carryback claim, and that computations should identify the period where the loss arose and the trade concerned. Box 45 flags relief affecting an earlier period. If the earlier-period return is still being completed, boxes 275 and 280 identify the later-period loss.
The result is a recalculation of earlier tax, so do not multiply £28,400 by today's rate. Earlier rates, marginal relief and existing claims can all change the figure. A repayment can also be reduced by other Corporation Tax the company owes, so put no amount in the cash forecast until the recalculation and that check are done.
We suggest one working paper showing the window dates, each overlapping return, relief already used, the day count, the recalculated tax by period, the claim deadline and the actual credit or repayment. This is our practical suggestion, not an HMRC form. Record the unused £1,600 separately from the £28,400 claimed, so the working preserves the correct balance for potential future relief.
Sources and context, checked :