
US backup withholding: settle the gross bill and keep the tax payable
A $3,000 contractor bill can clear with $2,280 sent to the contractor and $720 still owed to the IRS. Once missing-TIN backup withholding has been established, the payment file must preserve the gross service amount, net cash and withholding liability separately. The net bank transfer does not describe the whole transaction.
Establish the payment's status first
The following example concerns a direct business service payment to a correctly classified, nonexempt US individual contractor in 2026. The reporting owner has already established that it is reportable nonemployee compensation and that 24% missing-TIN backup withholding applies. The payer genuinely holds no taxpayer identification number at payment.
That assessment comes before the arithmetic. An incomplete vendor form alone does not settle payee exemption, worker classification or which reporting rules cover the payment. Foreign-person withholding, card or platform settlement, and an IRS incorrect-TIN notice can require different work. A TIN omitted from a transmission despite being held by the payer is also a different fact pattern.
The 2026 information-reporting material uses a $2,000 threshold for the relevant nonemployee payments, rather than the older $600 amount. The assumed $3,000 payment exceeds it. The awaiting-TIN exemption of up to 60 days applies to specified categories such as certain interest payments; it does not give nonemployee compensation a general grace period.
Sources and context, checked :
- IRS General Instructions for Certain Information Returns (2026), Part N: backup withholding
- IRS General Instructions for Certain Information Returns (2026), Part N: missing TINs and reporting withholding
- IRS Understanding your CP2100 or CP2100A notice: missing TINs
- IRS General Instructions for Certain Information Returns (2026): increase in reporting and backup-withholding threshold
Clear the payable without losing the $720
All amounts and circumstances here are hypothetical. The business already owes the contractor $3,000 for supported services. It pays by direct bank transfer, with no gross-up, exemption or other adjustment. Backup withholding is $3,000 × 24% = $720. The contractor receives $3,000 minus $720, or $2,280.
The settlement debits accounts payable $3,000, credits bank $2,280 and credits a backup-withholding payable $720. Debits and credits balance, and the contractor payable clears in full. The $720 has changed who is owed the money; it has not become a second service expense.
When the business properly remits that $720 under the applicable Form 945 rules, it debits the withholding payable and credits bank. Combined cash paid is $2,280 to the contractor plus $720 to the IRS, equalling the original $3,000 liability. Until remitted, the withholding remains an outstanding obligation even though the supplier ledger is clear.
| Event | Debit | Credit |
|---|---|---|
| Settle service payable | Accounts payable $3,000 | Bank $2,280; withholding payable $720 |
| Remit withholding | Withholding payable $720 | Bank $720 |
Route the tax through Form 945
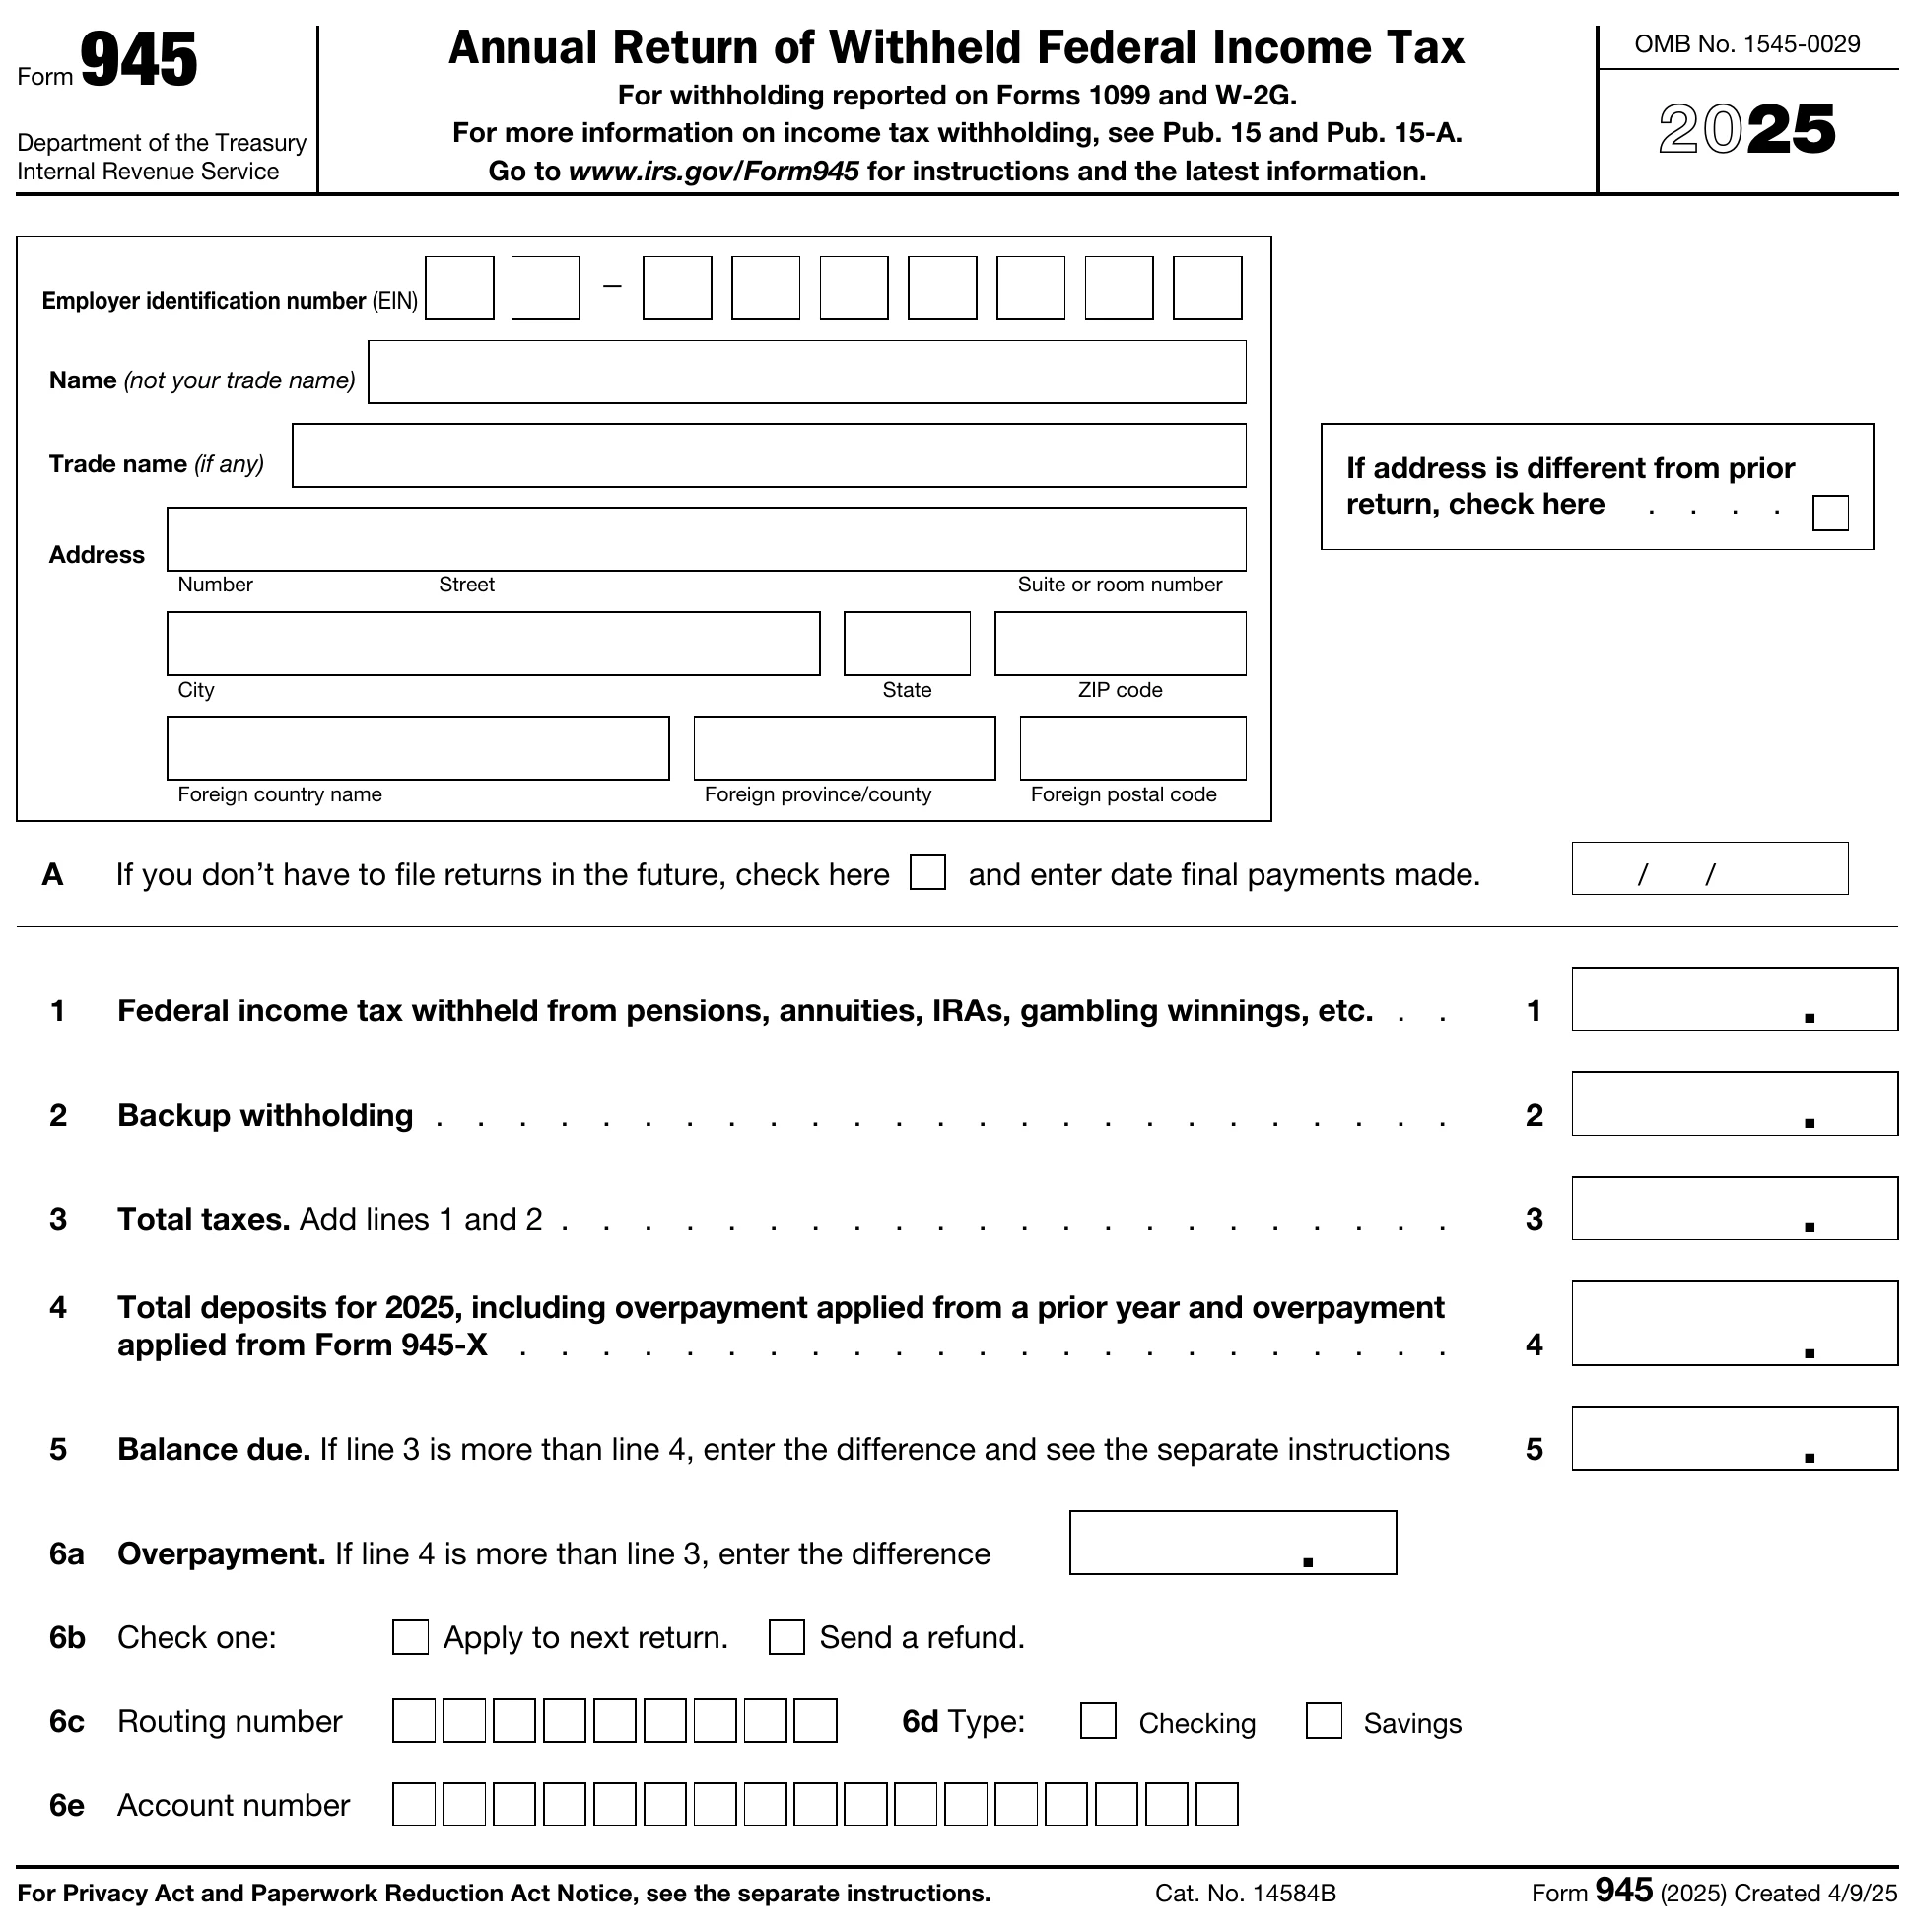
Form 945 reports federal nonpayroll income-tax withholding, including backup withholding. Review the business's combined Form 945 liabilities under its applicable deposit rules. Do not combine those taxes or deposits with the Form 941 wage-tax process merely because both payments go to the IRS.
One $720 invoice calculation cannot establish its deposit deadline. The whole Form 945 position and applicable rules matter. Equally, the existence of an annual return does not mean the payer can always wait until that return to pay. Keep the payment owner, timing assessment and confirmation with the withholding balance.
The source Form 945 illustration is a historical 2025 form. It helps distinguish liability from payments but is not a completed 2026 template or authority to copy a prior-year filing deadline.
Sources and context, checked :
Keep gross payment and withholding in the annual file
For the payee information-return file, preserve the $3,000 gross payment and $720 withholding. Recording only the $2,280 bank transfer would understate the service payment and lose the tax withheld. When backup withholding occurs, the appropriate information return must report it even when the payment falls below the ordinary reporting threshold.
The contractor generally claims the reported withholding as a credit for the year the income was received. That does not determine its final tax bill or promise a refund. The payer's close-out check is narrower: gross payment supported, net payment confirmed, $720 payable reconciled and the correct reporting route assigned.