
Form 8990: reconcile business interest before applying the deduction limit
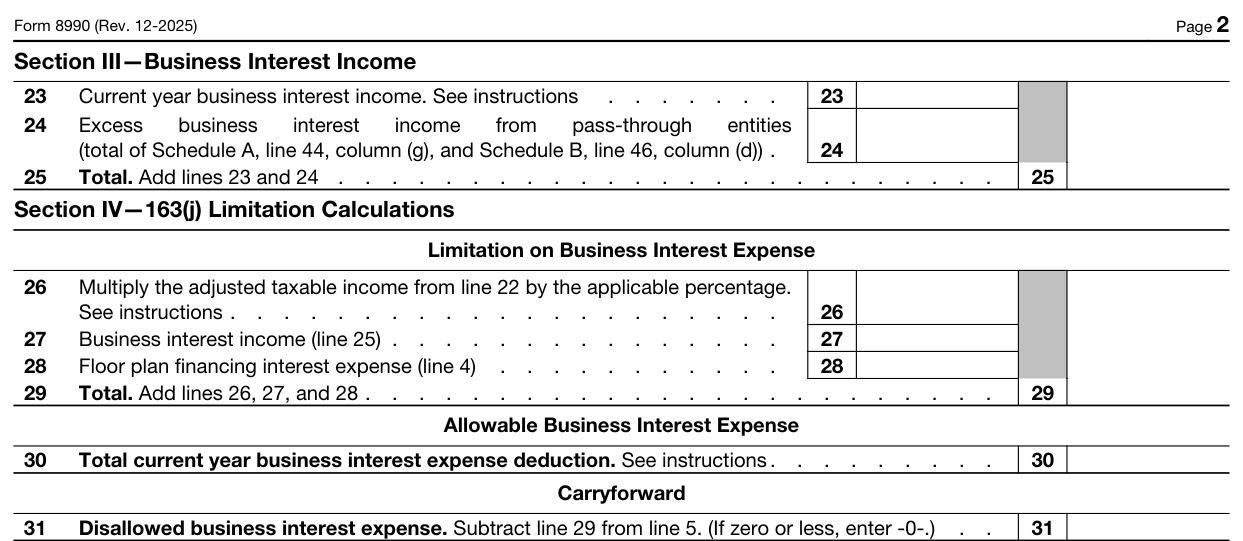
Start by asking whether the section 163(j) business interest limit applies at all. If it does, reconcile current business interest expense and prior disallowed interest as one tested balance, and build adjusted taxable income (ATI) as a separate tax computation. In the 2025 hypothetical below, a corporation testing $245,000 of interest deducts $151,000 and carries $94,000 forward.
Screen the small business exemption
A taxpayer that is not a tax shelter is generally exempt if its average annual gross receipts for the three prior years are at or below $31 million for 2025, or $32 million for 2026. Aggregation and related rules can combine receipts, and a tax shelter cannot use the exemption at any size.
In the hypothetical, a standalone calendar-year US C corporation with no controlled group, short period or exception had applicable gross receipts of $33 million, $34 million and $35 million. The $34 million average is above the 2025 screen, so it files Form 8990.
Reconcile the interest balance
Lines 1 to 5 bring current business interest expense together with the disallowed carryforward. Tie the current figure to a debt and loan interest schedule that agrees with the general ledger after tax adjustments. Take the prior carryforward from last year's Form 8990 line 31 and confirm what was allowed. Here, $210,000 of current interest plus a $35,000 prior disallowance gives $245,000 on line 5.
Keep business interest income separate from expense. If included in tentative taxable income, subtract it when calculating ATI, then include it separately when calculating the limit.
Sources and context, checked :
Build ATI from tentative taxable income
Start from tentative taxable income on line 6. For tax years beginning after 2024, add back depreciation, amortization and depletion as applicable. The hypothetical has $185,000 of tentative taxable income. That includes current interest expense and business interest income and excludes the $35,000 prior disallowance. Assume no other adjustments.
| Item | Amount |
|---|---|
| Line 6 tentative taxable income | $185,000 |
| Add current business interest expense on line 8 | $210,000 |
| Add allowable business depreciation | $85,000 |
| Less business interest income | ($10,000) |
| ATI on line 22 | $470,000 |
Apply the limit and carry the rest
The limit is business interest income plus 30% of ATI plus any eligible floor plan financing interest, none here. That is $10,000 + 30% × $470,000, or $10,000 + $141,000 = $151,000. Of the $245,000 tested, $151,000 is deductible and $94,000 is disallowed and carried forward on line 31.
The cap delays the deduction. It does not change the interest recorded in the books. Partnership excess interest rules, elections, group rules and 2026 changes fall outside this example.
Copy the $94,000 closing disallowance into next year's workpapers now, with the gross receipts analysis attached.
Sources and context, checked :