
Form 3800: track general business credit carryforwards by year
A general business credit carryforward is only auditable if it keeps the credit type, origin year, prior use and every change behind the closing number. Track it by credit and by year, not as one running total. In the 2025 hypothetical below, the $4,000 carried into 2026 still originates in 2024.
The carry rules your schedule must reflect
As a general rule, an unused credit is carried back one year and then forward up to 20 years. That does not hold for every credit. Some clean energy and marginal well credits have longer carrybacks, and a credit generally cannot be carried back to a year before its first allowable year. Form 3800 uses the earliest carryforward before later carryforwards and current-year credits, and Part II sets the tax limit.
Sources and context, checked :
Hypothetical 2025 roll-forward
A calendar-year taxpayer has two documented remaining carryforwards of the same ordinary nonpassive credit, $8,000 from 2023 and $6,000 from 2024. Carryback analysis was done when each arose and neither has expired. Part II allows $10,000 of these credits in 2025. There is no current credit, carryback into 2025, recapture, transfer, ownership change or passive limit.
The $14,000 opening balance is used oldest first, $8,000 from 2023 and then $2,000 from 2024. The $4,000 left is still a 2024 credit. Relabeling it as 2025 would misstate its expiration year.
This oldest-first illustration covers one credit in one category. It does not replace Form 3800 ordering, credit-specific limits or passive limits.
| Origin year | Carried into 2025 | Used in 2025 | Carried into 2026 |
|---|---|---|---|
| 2023 | $8,000 | $8,000 | $0 |
| 2024 | $6,000 | $2,000 | $4,000 |
| Total | $14,000 | $10,000 | $4,000 |
Sources and context, checked :
Where the year detail appears
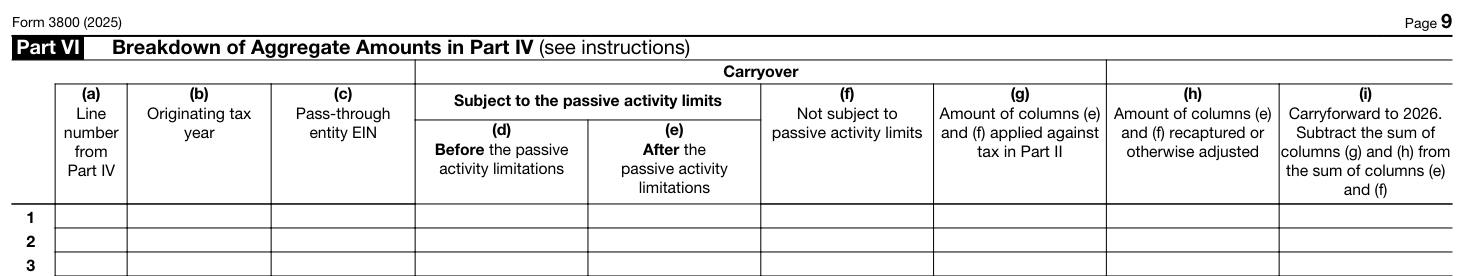
Part IV columns b to i summarize carryovers, use, recapture and the closing carryforward. Part VI breaks down amounts aggregated from more than one tax year or more than one pass-through entity. It reports the originating year and the pass-through entity's employer identification number (EIN) where applicable. In the example, Part IV shows the aggregate and Part VI breaks the reported amount down by year.
If you are submitting a revised carryforward, read the IRS required-statement instructions first.
Sources and context, checked :
Rebuild the schedule
Give each credit and origin year its own row with these columns.
Keep the source forms, prior returns with Form 3800, any amended returns or audit changes, and the tax-limit workpaper. Then reconcile your opening balance to the last filed closing balance and document any difference before the 2026 return is prepared. Original credit calculations, transfers, elective payments and ownership change rules sit outside this schedule.
- Source credit form or Schedule K-1, with the issuer's EIN if applicable
- Eligible carryback reviewed and used
- Prior years' use and the carry-in
- Current allowed use, recapture or adjustments
- Expiration year and carry-out
Sources and context, checked :