
Form 7004: estimate the tax before extending the business return
Hypothetical: a C corporation's books are not ready, so the return coordinator plans to file Form 7004 and sort out the numbers later. The extension can buy time to file Form 1120. It does not move the date the tax is due. This article uses the Instructions for Form 7004 (revised December 2025) for domestic US federal business returns. It does not cover state extensions, foreign filers or special-period exceptions.
What the extension covers
Form 7004 requests an automatic extension of time to file certain business returns. The instructions say to file it by the regular due date of the return, complete it properly, make a proper estimate of tax where one applies and pay the tax due. The extension is usually 6 months, with listed exceptions.
Each return needs its own Form 7004, and the request covers only the return identified on Part I, line 1. The owners' individual returns are not among the returns it extends, so shareholders handle their own deadlines separately.
Sources and context, checked :
Identity details can void the request
The name and identifying number on the form must match IRS records. The instructions say a mismatch or incorrect number means the extension is not valid. The IRS sends notices when an extension is disallowed, not routine approvals, so the filer's own submission records are the evidence to keep.
Sources and context, checked :
Lines 6 to 8 are a tax estimate
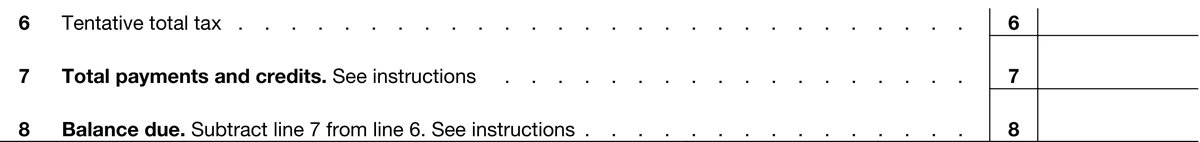
Line 6 is the tentative total tax, worked out under the instructions for the return being extended. Line 7 is total payments and refundable credits. Line 8 is the balance due. Form 7004 does not extend the time to pay, and interest on unpaid tax generally runs from the regular due date even when the filing extension is valid.
For corporations, the instructions describe an exception to the late-payment penalty under conditions tied to paying at least 90 percent of the tax by the regular due date and the balance by the extended due date. It does not stop interest or change when the tax is due. Read the exact conditions rather than treating 90 percent as the amount to pay.
Sources and context, checked :
A hypothetical estimate
This is an original hypothetical, not an actual filing. Assumptions: a domestic C corporation is preparing Form 1120 and files a valid, timely Form 7004. No foreign, June 30 year-end, short-period, disaster, carryback or other special rule applies. Its tentative total tax after nonrefundable credits is assumed to be $28,000. Confirmed estimated payments and refundable credits total $21,000. No calendar deadline is stated here; use the actual Form 1120 instructions for the year.
Filing the extension does not pay the $7,000. Interest and any penalty are not calculated in this example.
| Form 7004 line | Basis | Amount |
|---|---|---|
| Line 6, tentative total tax | Assumed computation | $28,000 |
| Line 7, payments and refundable credits | Confirmed payments and credits | $21,000 |
| Line 8, balance due | $28,000 - $21,000 | $7,000 |
Sources and context, checked :
Keep three separate records
The estimate, the extension and the payment are different tasks, and each needs its own evidence.
- Confirm the legal entity, IRS-record name and EIN, return code and exact tax period before transmitting.
- Tie line 6 to a dated tax computation and line 7 to actual payments and credits, not a remembered cash reserve.
- Pay the balance by the regular due date and save the payment confirmation separately from the extension acknowledgment.
- Calendar the actual extended filing date and the open accounting tasks, and check shareholder and state obligations on their own.
Sources and context, checked :
The question to answer first
Before deciding to extend, ask whether line 6 can be estimated from the current books. If it cannot, the gap is in the tax computation, and an extension does not close it.
Sources and context, checked :