
Restaurant tip credit: build Form 8846 from monthly payroll records
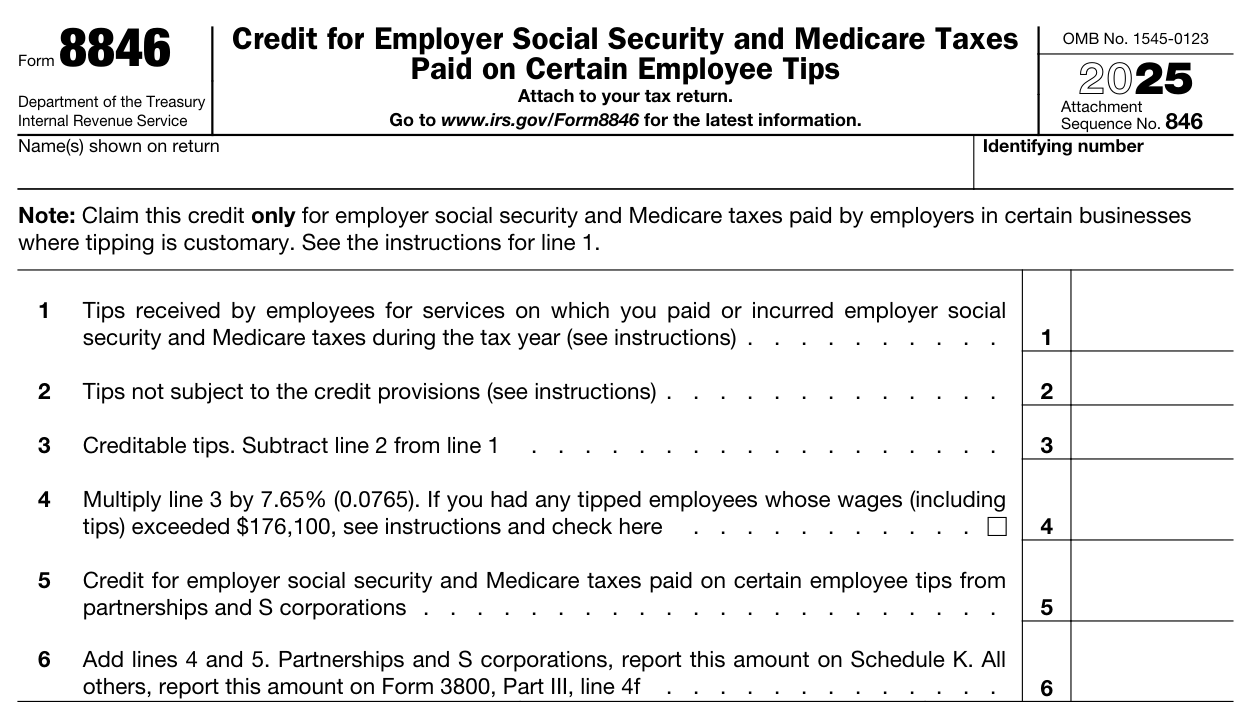
Form 8846 starts with reported tips on which the restaurant paid or incurred employer Social Security and Medicare tax. For each employee and month, remove the tips needed to bring wages excluding tips up to $5.15 an hour. Multiply the remaining tips by the applicable employer rate. Mandatory service charges distributed to employees are non-tip wages and are not creditable tips, and they can affect the monthly wage comparison.
The question before the return
At year end, a restaurant bookkeeper has a payroll system full of tip data and one question to settle before the return is prepared: which of those tips support the employer's credit on Form 8846? The answer has to be built employee by employee and month by month.
The IRS describes the credit as an income tax credit for qualifying employer Social Security and Medicare taxes paid or incurred on employee tips. It is separate from the federal deduction employees may take for qualified tips, so keep the two in different workpapers.
The credit applies to tips received in connection with providing, delivering or serving food or beverages where tipping is customary.
Sources and context, checked :
How the form sequence works
Lines 1 through 4 of the 2025 final Form 8846 follow a short path. Start with tips on which employer FICA was paid or incurred, remove tips that are not creditable, and multiply what remains by the employer rate. The tips removed are those needed to bring each employee's wages excluding tips up to $5.15 an hour for the month. That figure is a historical reference built into the credit. It is not the current legal wage floor and says nothing about wage-law compliance.
The rate is subject to the Social Security wage base. Once an employee's wages and tips pass the base, only the Medicare portion applies to further tips, so 7.65% cannot be applied across the board. Use the Social Security limit for the calendar year in which the wages were paid, regardless of the tax year label on the return. If the limit is exceeded, the 2025 Form 8846 instructions provide a line 4 checkbox and an attached calculation that applies only the Medicare rate to applicable tips beyond the base. Employer taxes used to figure the credit cannot also be deducted.
Sources and context, checked :
A hypothetical month
Hypothetical, 2025: one covered restaurant employee works 80 hours in a month, receives $340 in direct wages excluding tips and reports $600 in qualifying tips. The employer paid or incurred standard employer FICA on the tips. There are no service charges, timing complications or Social Security wage cap issues, and all applicable wage laws are assumed met independently.
The $40.39 is a monthly input to the annual form. It is not the employee's tax on tips, it does not offset payroll deposits, and it is not the final usable credit. The $412 figure exists only for Form 8846.
| Step | Calculation | Result |
|---|---|---|
| Monthly reference amount | 80 hours × $5.15 | $412 |
| Tips excluded | $412 - $340 | $72 |
| Creditable tips | $600 - $72 | $528 |
| Monthly credit input | $528 × 7.65% | $40.392, or $40.39 before return-level rounding |
Sources and context, checked :
Keep service charges in their own category
The IRS treats mandatory service charges distributed to employees as non-tip wages. They are excluded from creditable tips, even when the point-of-sale report shows them beside tips. Where they apply, they count as non-tip wages in the monthly comparison against the $5.15 reference amount. A line on a POS report does not establish that a customer left a voluntary tip.
Employees report tips to the employer, and the employer maintains payroll records. Keeping POS reports and employee tip reports alongside payroll lets you explain cash tips and category differences when totals do not match.
Sources and context, checked :
Monthly records checklist
Build one row per employee per month, then reconcile the rows to the annual Form 8846.
Before the return is prepared, pull one month for one employee, rebuild the row by hand from payroll and tip reports, and confirm it matches the credit workpaper. Then extend the same layout to every covered employee.
- Hours worked in the month
- Wages excluding tips
- Qualifying tips reported by the employee
- Mandatory service charges, recorded as non-tip wages
- Monthly $5.15 reference amount and excluded tips
- Employer FICA paid or incurred, the rate used and wage base checks
- Links to the POS report and the employee's tip report
Sources and context, checked :