
Section 179 recapture when business use of retained equipment falls
Equipment deducted in full under section 179 can produce taxable income later without ever being sold. IRS Publication 946 says that if business use of section 179 property drops to 50% or less during its recovery period, part of the deduction may have to be recaptured. Exactly 50% is inside the trigger. The recapture is ordinary income, and it increases the asset's basis. This article covers non-listed property the taxpayer keeps. Vehicles and other listed property follow separate qualified business use tests under section 280F, and sales or exchanges follow separate rules.
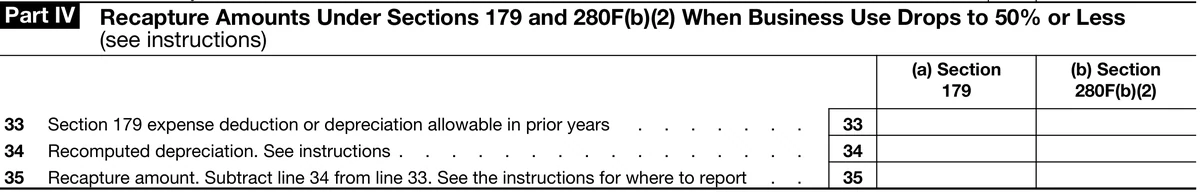
How the recapture is measured
Publication 946 sets out the calculation. Work out the depreciation that would have been allowable on the section 179 amount from the year the asset was placed in service through and including the recapture year, then subtract it from the section 179 deduction claimed. The current year's business-use percentage applies in the recomputation for the recapture year.
The result is therefore not the full original deduction. Only the part of the deduction that exceeds the recomputed depreciation comes back as income. If the asset is sold, exchanged or otherwise disposed of, Publication 946 points to the depreciation recapture rules in Publication 544 instead of this calculation.
Sources and context, checked :
A hypothetical recomputation
Hypothetical: one qualifying non-listed item of equipment cost $20,000 and was placed in service in 2024. The full $20,000 section 179 deduction was validly claimed, with no carryforward, and bonus depreciation was elected out. Assume five-year property under 200% declining balance MACRS with the half-year convention and full 12-month tax years. Business use was 100% in 2024 and 2025 and 40% in 2026. The asset was not sold. The class, method and convention are assumptions for this example, not a statement that all equipment is five-year property.
For that class, method and convention, Publication 946 Table A-1 gives rates of 20%, 32% and 19.20% for years one to three.
On these assumptions, $8,064 is recaptured in 2026 and added to the asset's basis. The original $20,000 is not recaptured in full. The example does not compute depreciation for later years.
| Step | Calculation | Amount |
|---|---|---|
| 2024 recomputed depreciation | $20,000 x 20% | $4,000 |
| 2025 recomputed depreciation | $20,000 x 32% | $6,400 |
| 2026 recomputed depreciation | $20,000 x 19.20% x 40% | $1,536 |
| Total recomputed depreciation | $4,000 + $6,400 + $1,536 | $11,936 |
| Section 179 recapture | $20,000 less $11,936 | $8,064 |
Sources and context, checked :
Reporting the amount
The IRS Instructions for Form 4797 direct section 179 recapture for non-listed property to Part IV, column (a). Listed property generally uses column (b) under section 280F(b)(2). Each affected asset is calculated separately, with a statement attached if there is more than one.
The recapture amount is reported as other income on the form or schedule where the original deduction was taken, such as Schedule C for a sole proprietor. That is a separate step from computing gain on a sale. Use the form and instructions for the year actually being filed.
Sources and context, checked :
Watch business use every year
Recapture is easy to miss because nothing happens to the asset itself. A yearly review of section 179 assets should cover the following.
- Every asset with a section 179 deduction and the end of its recovery period.
- The original election, the deduction actually allowed, the class, the convention and the schedule where it was claimed.
- Business and personal use for the year, measured with a supported method.
- Retained assets at 50% business use or lower, with listed property separated out and a calculation kept for each asset.
- The recapture income and basis increase recorded in the tax records.
Next action
Add a business-use percentage column to the fixed asset register for every section 179 asset still inside its recovery period, so a drop is spotted in the year it happens. Book depreciation in the register does not need to change merely to match the tax recapture.