IFRS 18 in 2027: a preparation guide for IFRS reporting teams
IFRS 18 applies to annual periods beginning on or after 1 January 2027. Confirm your first period, plan the restated comparatives and map your public performance measures now.

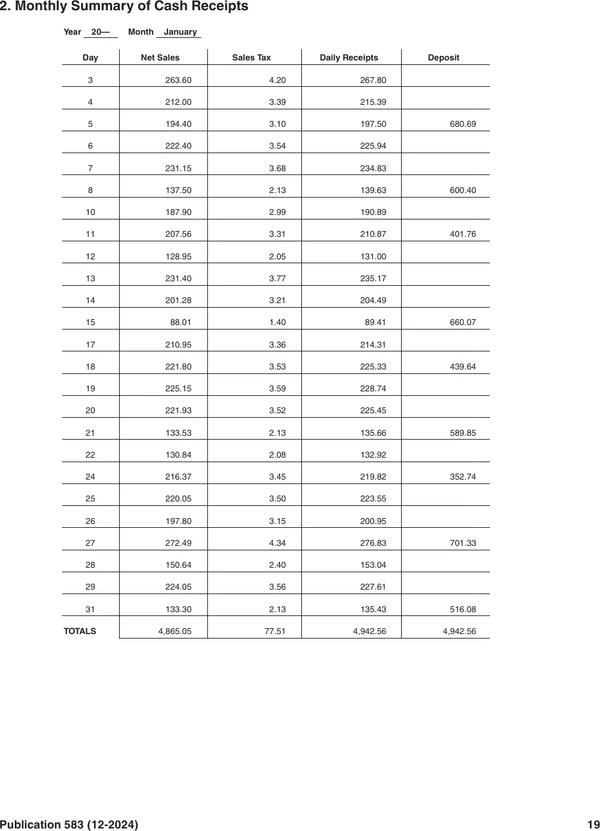
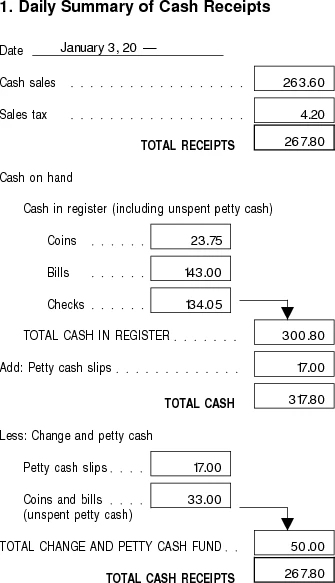
Keep the books in order, plan for cash needs and understand reporting changes. Practical guides with worked examples and links to the evidence.
IFRS 18 applies to annual periods beginning on or after 1 January 2027. Confirm your first period, plan the restated comparatives and map your public performance measures now.
A month-end close checklist built around one test: can someone who did not prepare the accounts trace each balance and see every open item?
Agree the output, reviewer, systems and legal basis for access before an offshore team opens a client file, then test one closed month.
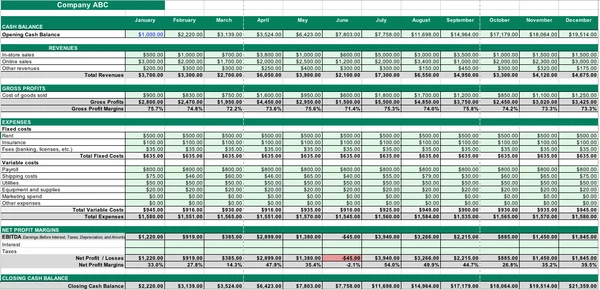
A worked example shows how 6,000 of profit can sit beside a 1,000 operating cash outflow, and how a loan can hide that in the bank balance.
HMRC sets your start date from gross self-employment and property income in an earlier tax year. Here are the thresholds, the November 2026 deadline and the records to prepare.
Purchasing costs above budget? Split the overrun into a price effect and a quantity effect, then check supplier rates, activity and stock before changing the forecast.