
Annual investment allowance: prove the tax date before claiming
A £24,000 machine arrives on 20 December 2026, the year end is 31 December, and the bank pays on 19 January 2027. On normal delivery terms the cost can enter the 2026 annual investment allowance (AIA) claim, because capital expenditure normally counts when the obligation to pay becomes unconditional. The bank entry proves the payment and the fixed asset entry proves the booking. Neither shows the tax date, the eligible cost or how much allowance is left.
Find the date the obligation became unconditional
AIA can only be claimed in the period of purchase. HMRC's Capital Allowances Manual gives the more exact test: expenditure is normally incurred when the obligation to pay becomes unconditional. That is not simply the order, invoice or bank date. For a normal goods purchase it may be delivery. The manual also separates this date from the date payment is legally due.
HMRC's shorter public guide explains timing more simply by reference to the contract date, so work from the contract terms and the manual's detail.
One exception can move the date. If more than 4 months separate the unconditional obligation from the date payment is due, the expenditure is incurred on the due date. Instalments may need splitting.
Hire purchase has its own use-date and interest rules, so the example below leaves it out. The US placed-in-service test has no role in a normal UK outright purchase.
Sources and context, checked :
Test the December machine
This hypothetical company has a 31 December 2026 year end, eligible machinery, no VAT in the tax cost, no special contract, no hire purchase and enough unallocated AIA. Normal delivery terms make the obligation unconditional on 20 December.
On those facts, £24,000 may enter the 2026 claim if the remaining eligibility and allowance checks pass. One changed term would move the answer. If the contract had made payment due on 30 April 2027, the gap from 20 December would exceed 4 months and the expenditure would fall on 30 April, outside the 2026 period.
| Event | Date | Effect on the tax date |
|---|---|---|
| Delivery on normal terms | 20 December 2026 | Obligation becomes unconditional |
| Year end | 31 December 2026 | Expenditure falls inside the period |
| Invoice due date | 19 January 2027 | Within 4 months, so no deferral |
| Bank payment | 19 January 2027 | Shows settlement only |
Check the cost and the allowance left
AIA can deduct the full qualifying value of most plant and machinery, up to £1 million for a 12-month period. Cars, gifts and items already owned for another purpose are excluded, and a short period reduces the limit. The £1 million is a ceiling on a deduction, not a refund. Tie each amount to the invoice, remove recoverable VAT where relevant and do not assume every invoice cost qualifies.
Then check group and related-company restrictions, because a separate company does not automatically bring a fresh allowance. A company group shares one AIA. Separate companies or groups under common control share only when they are related under the shared-premises or similar-activities conditions in HMRC's manual, so work through those conditions for your own structure.
AIA is optional. Full expensing and writing-down allowances are separate routes, and AIA is unavailable in the final accounting period when the business closes.
Build the claim from a tax additions schedule
A company claims through its Company Tax Return. An AIA claim can create or increase a loss, so settle the amount before finishing any loss working.
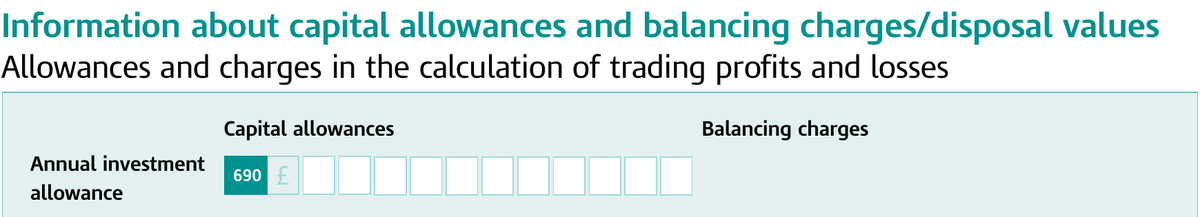
We suggest a tax additions schedule kept apart from depreciation. This is our practical control, not an HMRC form. Give each asset one row showing why it is eligible plant or machinery, the invoice cost and tax cost, the contract or delivery evidence, the date the obligation became unconditional, payment due dates and instalments, and the AIA allocated after allowing for period length and any shared limit. Trace the total through the tax computation to CT600 box 690.
If a row has only a bank date, hold that item out of the claim until you have the contract or delivery record.
Sources and context, checked :