
Worker classification: keep the evidence behind the contract
A contract that calls someone an independent contractor does not settle their status for federal employment tax. The IRS looks at the whole relationship, including who has the right to direct the work and who carries the business risk. Your file should show how the work actually runs, because the label alone cannot prove it.
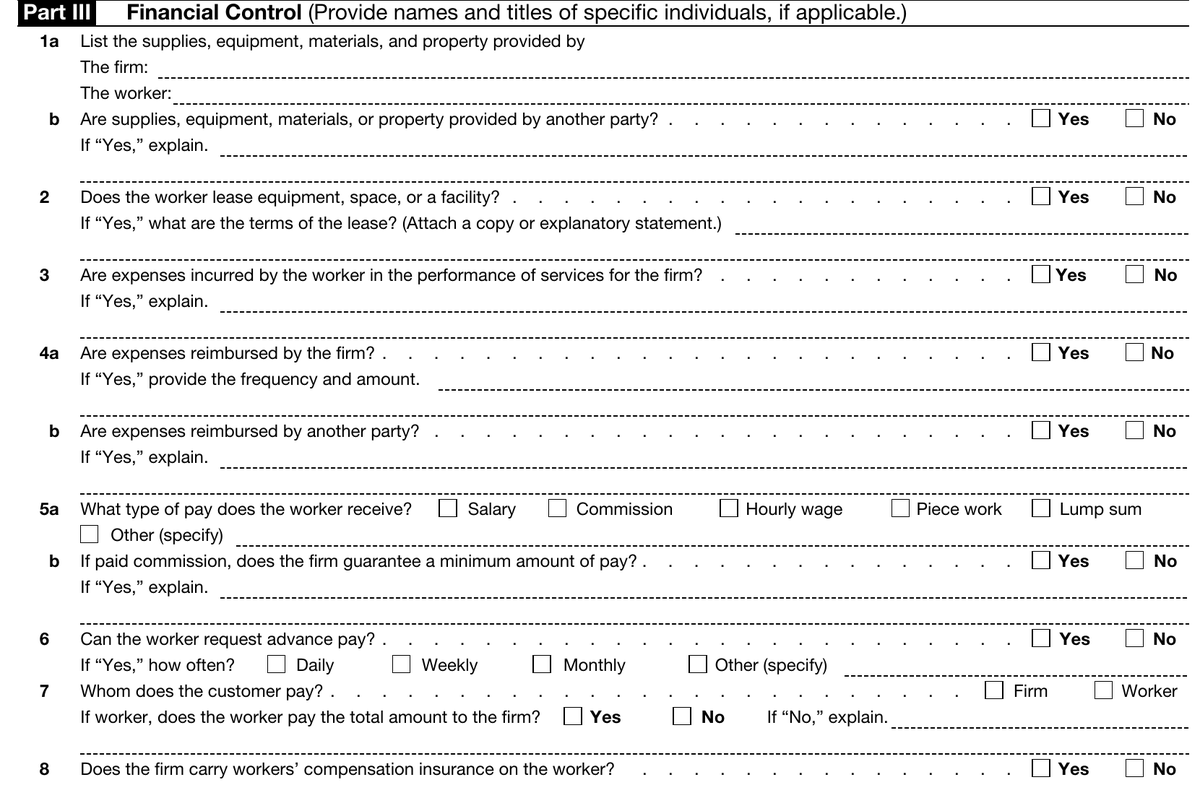
Why the contract is only one document
The IRS says a written contract describing a worker as an independent contractor is not enough to establish that status. Its common-law guidance looks at substance. If the business has the right to control what is done and how it is done, that right establishes an employee relationship even if the business allows the worker freedom in practice. Calling the role full time or part time does not change the analysis.
There is no scorecard. The IRS says there is no magic number of factors and that no one factor stands alone, so you weigh the whole relationship and document the factors you used. A completed Form W-9 or a signed agreement answers narrower questions. Neither settles the actual relationship by itself.
Sources and context, checked :
Evidence in each IRS category
The IRS sorts the evidence into behavioral control, financial control and the type of relationship. We suggest recording facts that point in either direction, including those that weaken the answer you expected.
| Category | Evidence to keep | How to read it |
|---|---|---|
| Behavioral control | Instructions on when and where to work, tools, sequence and methods; training records; how work is evaluated | Instructions and training in how to do the job point toward control. A right to control methods can matter even if no instructions are given. Evaluating results alone can point either way. |
| Financial control | Investment, unreimbursed expenses, invoices, evidence of services offered to others, terms that create profit or loss | These facts help assess independence, but no precise investment amount settles it. Hourly pay is not conclusive, since some independent contractors are paid that way. |
| Type of relationship | Contract, benefits, expected length, whether the services are a key activity of the business | Employee-type benefits, an indefinite relationship and services that are a key activity are relevant evidence. The contract wording is not enough by itself. |
Sources and context, checked :
Two hypothetical files
This hypothetical evidence review is not an IRS determination. A business calls its bookkeeper a contractor and pays their invoices. The manager sets a daily schedule, requires the firm's step-by-step procedures, provides ongoing training in those methods and reimburses all expenses. That file holds substantial evidence of behavioral and financial control, whatever the contract says.
A second provider agrees a monthly reporting result, chooses how and when to produce it, markets services to others and pays the cost of correcting errors. That file contains evidence of independence. It still does not establish status, because a short example leaves out the rest of the relationship and any special rules.
Sources and context, checked :
What to put in the file
The IRS advises businesses to document the factors used in deciding status. The format below is our suggestion, not an IRS requirement.
- A plain description of the work actually done, and who may change the methods.
- Copies of instructions, training records, contracts, invoices and equipment or expense arrangements.
- A note of the facts pointing each way across all three categories.
- The name of the person who made the decision, the basis for it and a review date.
Sources and context, checked :
If the answer stays unclear
Either the business or the worker can file Form SS-8 and ask the IRS to determine status. The form also shows what the IRS asks about, including training and instructions, work assignments, methods, equipment, expenses and reimbursement. The IRS says a determination can take at least six months. Do not treat a pending request as a pause on your filing and payment obligations. Keep them current and get advice while you wait.
All of this concerns federal employment taxes and income-tax withholding under common-law rules. State wage, unemployment and workers' compensation tests can differ, as can federal labor-law standards. Special rules, including those for statutory employees and nonemployees, can also apply.
Build the file before the worker enters your tax-reporting workflow, then reopen it on the day the work changes. If a manager introduces mandatory daily methods for a provider who used to work independently, the old label may no longer describe the relationship.