Non-refundable setup fees: what did the customer receive?
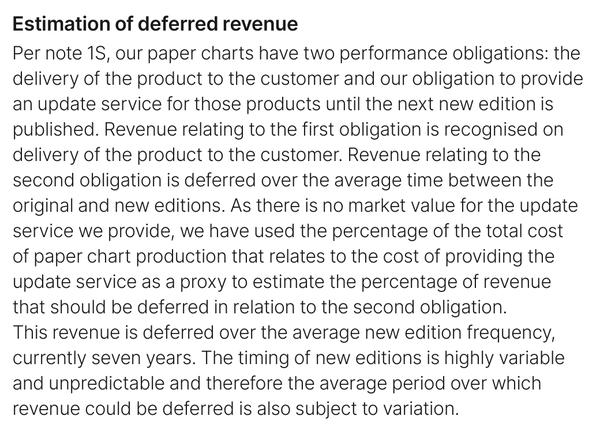
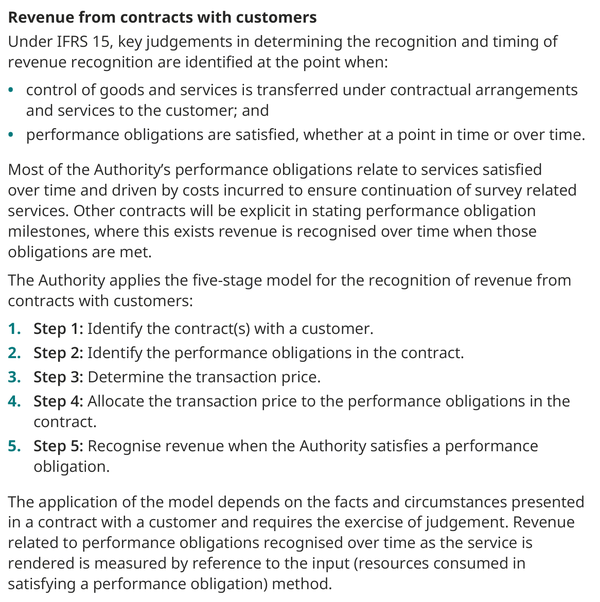
A non-refundable activation fee can still pay for future service. How to test setup activity under IFRS 15 and spread the fee when nothing separate transfers.

Keep the books in order, plan for cash needs and understand reporting changes. Practical guides with worked examples and links to the evidence.
A non-refundable activation fee can still pay for future service. How to test setup activity under IFRS 15 and spread the fee when nothing separate transfers.
Why a list price cannot simply be presumed to be the stand-alone selling price under IFRS 15, and what evidence supports splitting a bundled equipment sale.
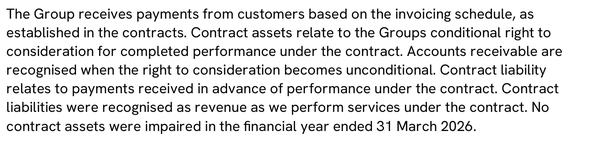
An earned balance can remain conditional after revenue recognition. Follow one milestone through contract asset, receivable and cash without recording revenue twice.
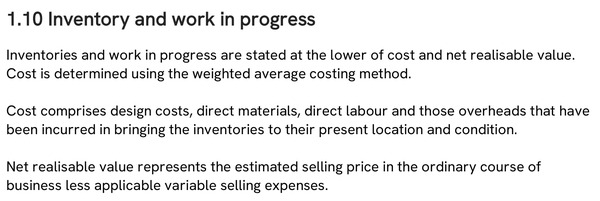
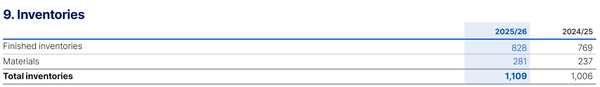
Low output does not justify putting every fixed factory cost into fewer units. A normal-capacity calculation separates inventory cost from unused-capacity expense.
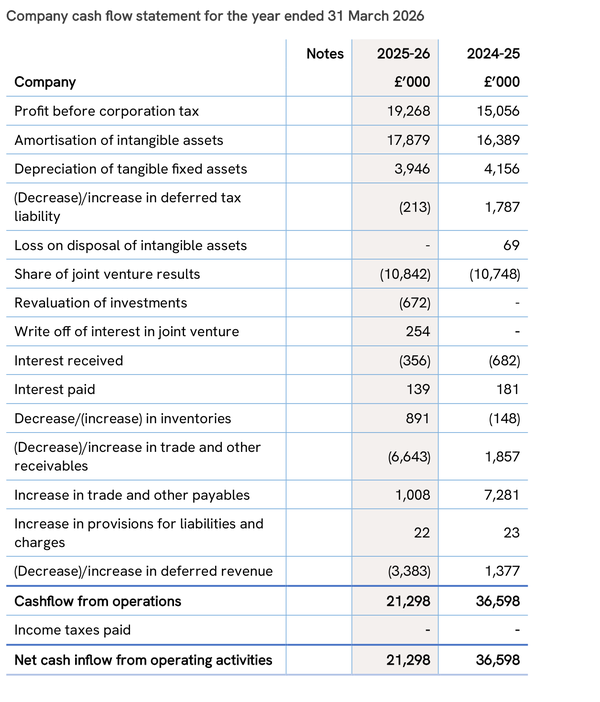
A stock write-down and an unpaid equipment purchase can distort an indirect cash-flow bridge. Reconcile the movements, then check against receipts and payments.
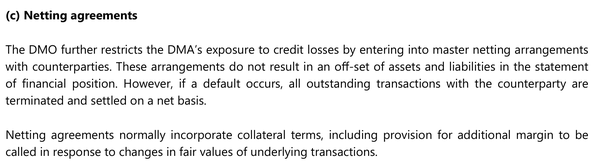
A net amount requires both an enforceable current set-off right and the intended settlement process. Test those conditions before combining customer and supplier balances.
A cost-based progress measure must reflect performance transferred to the customer. Remove unexpected waste from the progress calculation while keeping its expense.
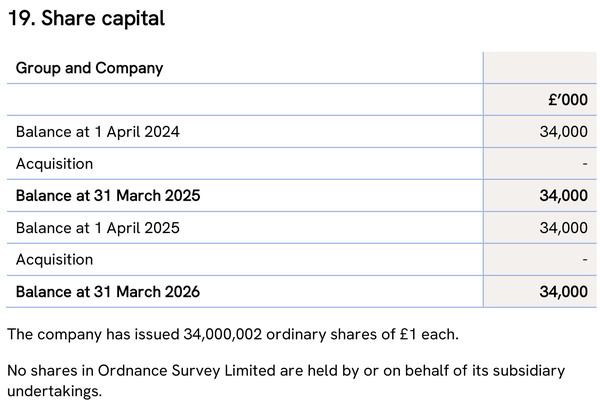
Shareholder identity and share labels do not settle classification. Compare a demand loan, ordinary shares and mandatory redeemable preference shares under IAS 32.
An earned purchase rebate changes the cost of both sold and unsold units. Allocate it before treating the whole credit as this period's margin improvement.
A partial lease termination and the revised payment valuation are separate steps. Follow a space reduction through the right-of-use asset, liability and gain.
A qualifying sale and leaseback retains some use of the asset. Separate that retained right from the rights transferred before measuring the recognised gain.
The programme liability and the amount already paid to suppliers are different figures. Build the opening and closing disclosure from invoice-level records.