US equipment depreciation: prove when the machine was ready
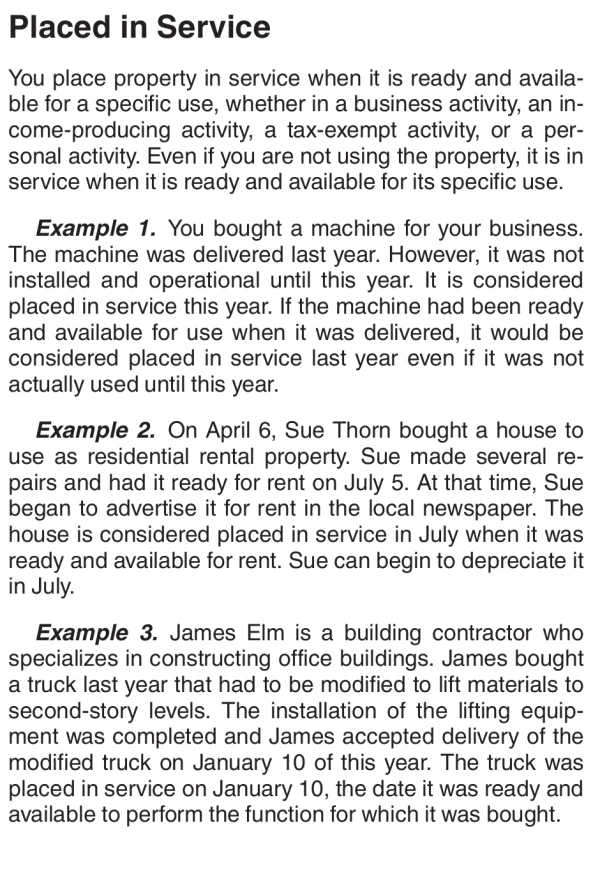
A year-end equipment purchase can enter service in December or January. Compare delivery, installation and readiness before calculating a federal tax deduction.

Keep the books in order, plan for cash needs and understand reporting changes. Practical guides with worked examples and links to the evidence.
A year-end equipment purchase can enter service in December or January. Compare delivery, installation and readiness before calculating a federal tax deduction.
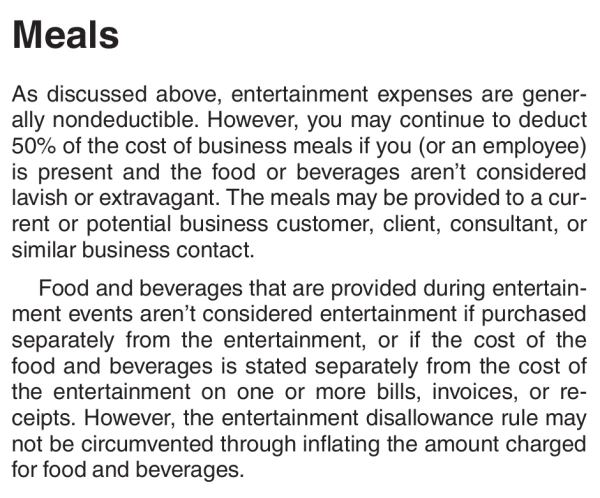
A hypothetical $840 client event yields a $120 federal deduction when qualifying food is separately charged. An internal estimate cannot fix a bundled bill.
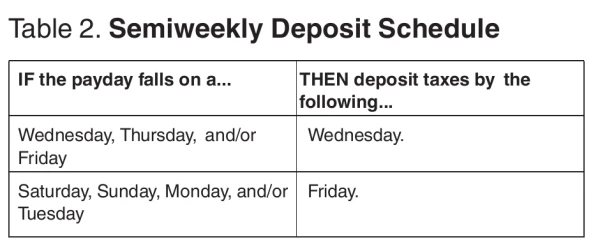
Choose the 2026 federal deposit schedule from the lookback, then reconcile actual payday, Schedule B liability and the separate bank payment.
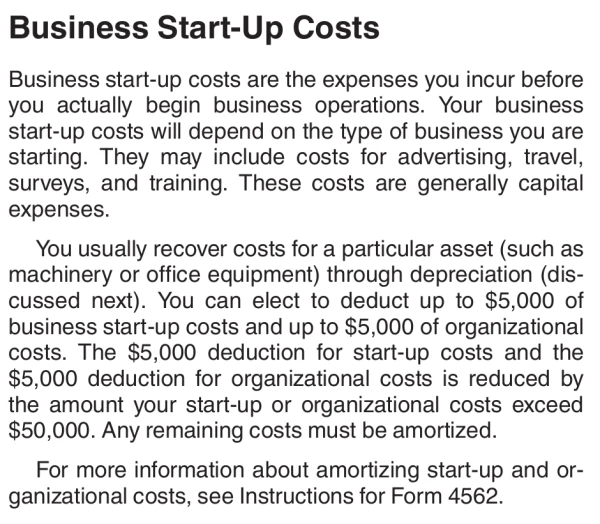
A hypothetical $23,000 startup-cost schedule produces a $5,300 first-year federal deduction. Qualification and the active-business start month come first.
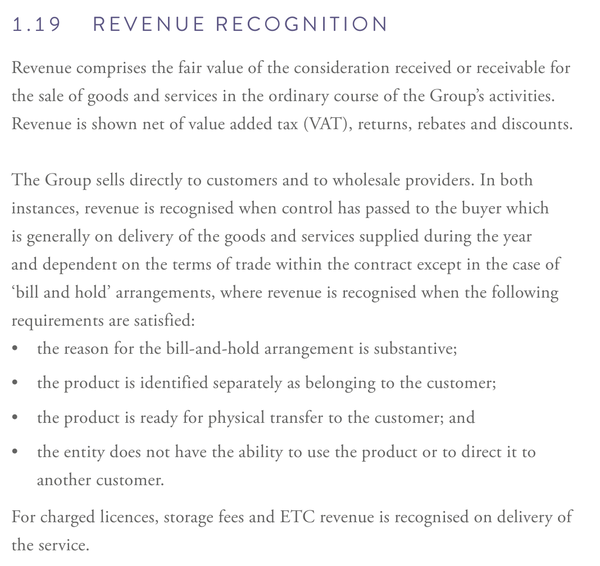
When product revenue can be recognised under IFRS 15 while goods stay in the seller's warehouse, and how to account for the storage service still owed.
When stock sent to a dealer is still the supplier's inventory under IFRS 15, and how to record revenue and cost of sales only when units sell through.
Why an associate's dividend reduces an equity-method investment instead of creating income, with a rollforward reconciling profit share, OCI and cash under IAS 28.
How to translate a subsidiary's functional-currency results into presentation currency under IAS 21 and explain the translation movement recognised in OCI.
How to assess an entity's functional currency under IAS 21 from what sets its prices and costs, and why invoicing, funding and presentation currencies differ.
When a coupon or renewal discount earned on a sale is a material right under IFRS 15, and how to price it, allocate revenue and release it on redemption or expiry.
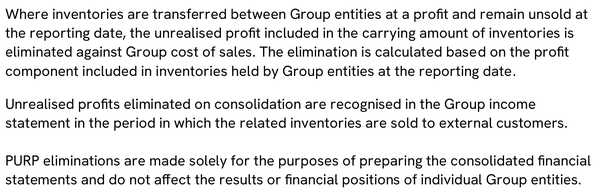
How to calculate and eliminate unrealised profit in intragroup closing inventory under IFRS 10, prove the group margin externally and release it next period.
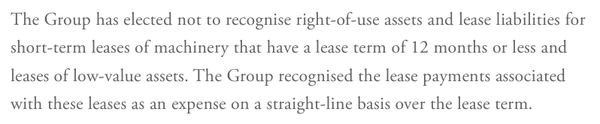
How to decide whether a lease qualifies for the IFRS 16 short-term or low-value exemption, with term, purchase-option and new-value tests and expense entries.