Related-party disclosure: what to report beyond the closing balance
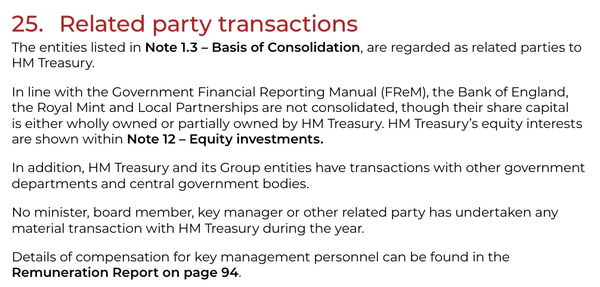
A £4,000 payable to a supplier the finance director controls reconciles cleanly. Under UK-adopted IAS 24, the note also needs the year's £18,000 and its terms.

Keep the books in order, plan for cash needs and understand reporting changes. Practical guides with worked examples and links to the evidence.
A £4,000 payable to a supplier the finance director controls reconciles cleanly. Under UK-adopted IAS 24, the note also needs the year's £18,000 and its terms.
100 units sold for £10,000 with 5 returns expected. Under UK-adopted IFRS 15 that means £9,500 revenue, a £500 refund liability and a separate £300 asset.
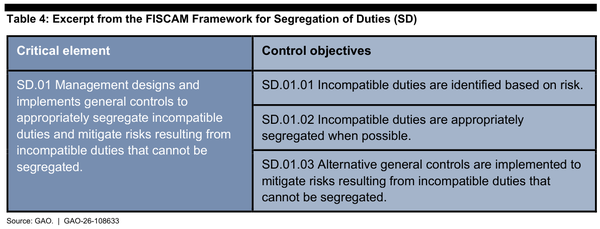
When one bookkeeper prepares, pays and reconciles, a signature on a total catches little. Map the overlaps and give a reviewer evidence that can find a bad payment.
A £100,000 ledger needs a £2,850 allowance, but this year's charge is £750. How UK-adopted IFRS 9 separates the allowance movement from a write-off.
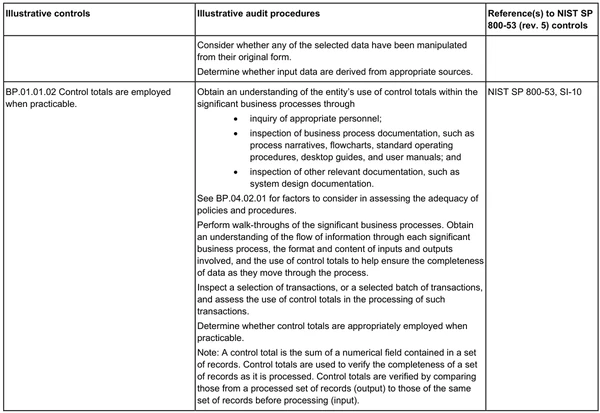
A journal file that lost one whole 500 entry still balances. Compare journal counts, row counts and gross debit and credit totals with the source, then check the mapping.
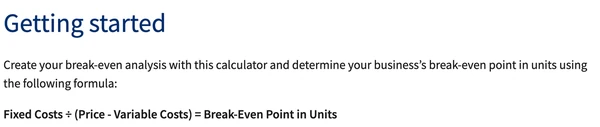
Taking 10% off a 50 price cuts unit contribution from 20 to 15. With 12,000 of monthly fixed costs, break-even rises from 600 units to 800.
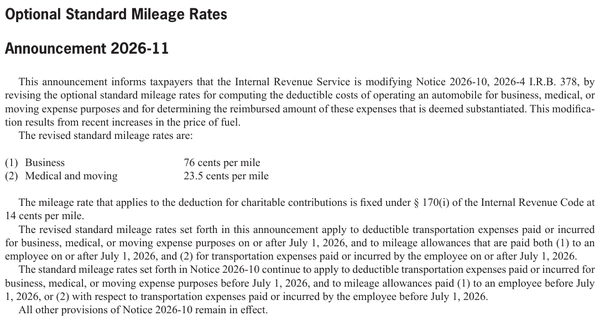
The IRS business mileage rate is 72.5 cents to 30 June 2026 and 76 cents from 1 July. A dated log of qualifying trips decides which rate applies to each mile.
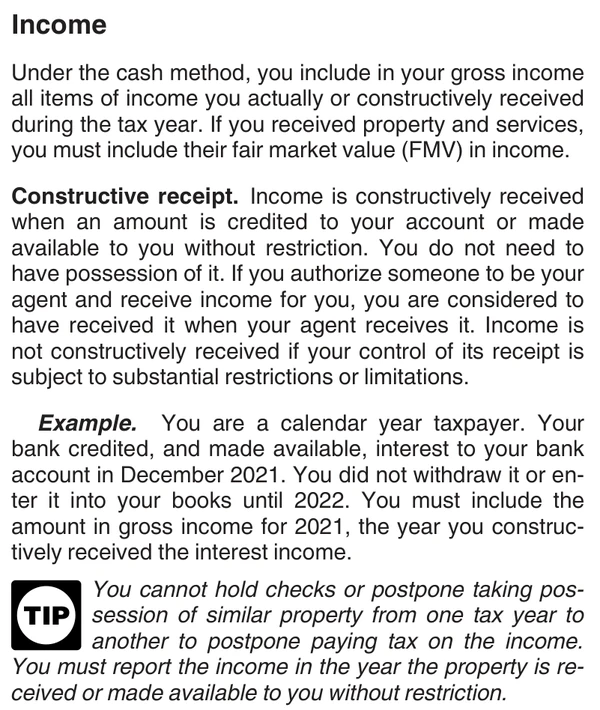
A valid $3,000 check is available on 31 December and deposited on 4 January. For a US cash-method federal return, the deposit date alone does not move it into the next year.
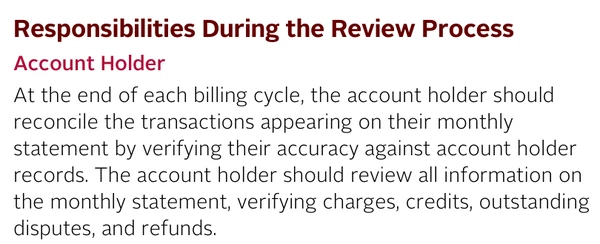
A 2,000 card repayment in the bank feed is not new spending. Roll the card liability forward from 1,000 to 1,250 and record each purchase, refund and fee once.
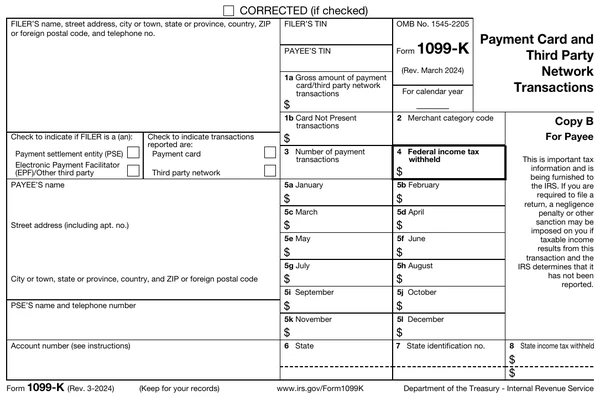
Two Forms 1099-K each report $40,000 for the same receipts. Prove the duplicate from transaction records, ask the issuer to correct it and keep a bridge to your books.
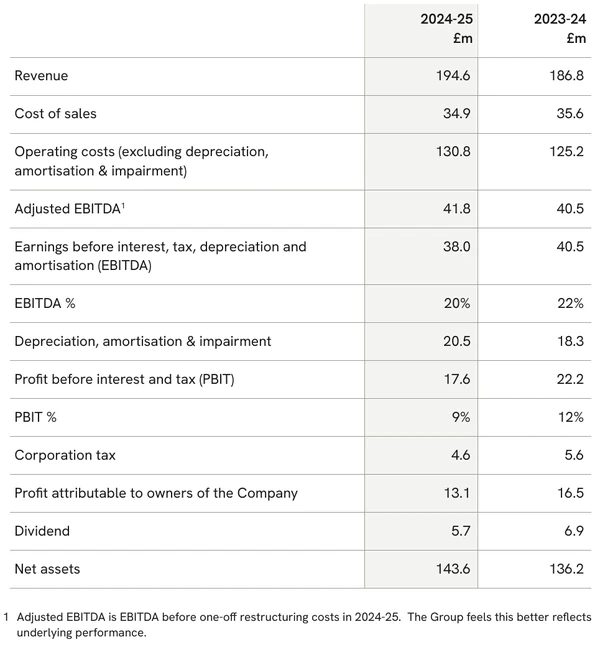
A published adjusted operating profit of 1,160 may be a management-defined performance measure under IFRS 18. Test the definition, then bridge it to IFRS operating profit with tax and NCI effects for each item.
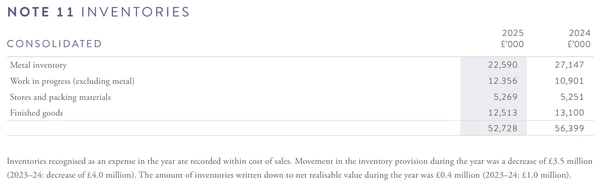
100 units costing 40 each may recover only 34 after finishing and selling costs. Write down 600 under UK-adopted IAS 2, then reassess without going above cost.