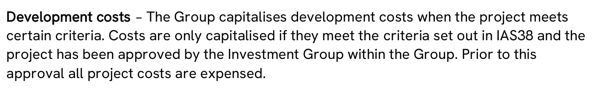
Development costs: capitalise only from the date all six tests are met
Under IAS 38, research is expensed and development enters the asset only once six criteria are evidenced. A software example shows why earlier spending stays expensed.

Keep the books in order, plan for cash needs and understand reporting changes. Practical guides with worked examples and links to the evidence.
Under IAS 38, research is expensed and development enters the asset only once six criteria are evidenced. A software example shows why earlier spending stays expensed.
Under IAS 1, a covenant due by year end affects debt classification even if the lender checks later. A late waiver does not change the year-end right.
A contract that covers its labour and materials can still be onerous. Under IAS 37, add directly related costs, test impairment first, then compare exit paths net.
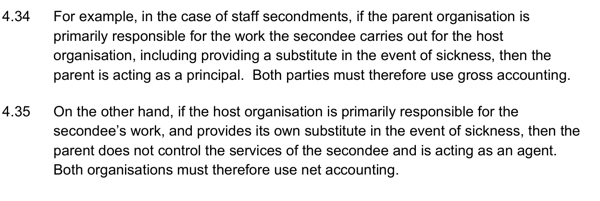
The same £20,000 receipt and £16,000 payout can mean £20,000 or £4,000 of revenue. Under IFRS 15, identify the service, then test who controls it.
Three small errors can move profit by a quarter. Under IAS 1, judge each error alone and together, by size and nature, with no universal cutoff.
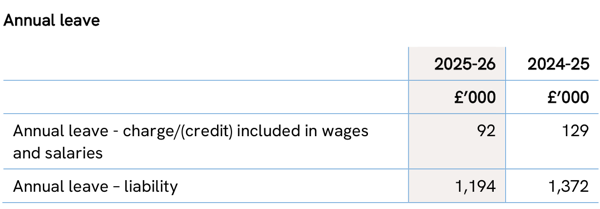
Under IAS 19, accumulating leave earned before year end is a liability even if not paid out on leaving. Three employees show the £1,760 accrual and the £360 top-up.
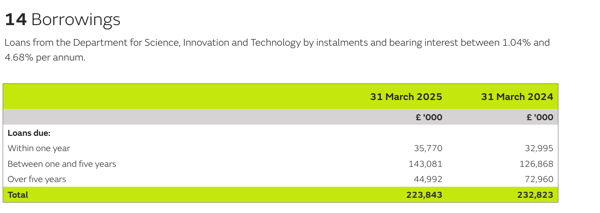
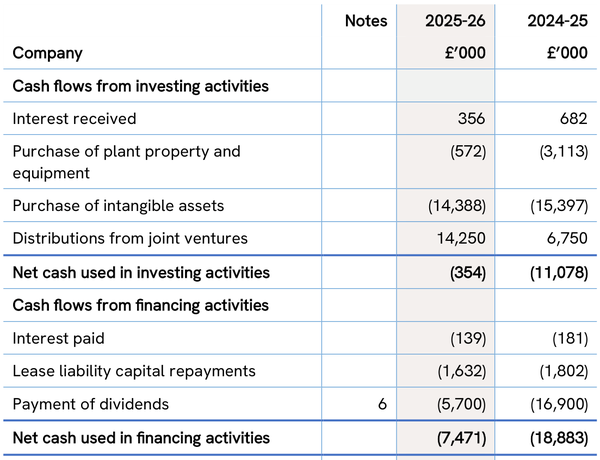
One £5,500 loan payment holds £5,000 of principal and £500 of interest. How IAS 7 classifies each part in 2026, and what IFRS 18 changes from 2027.
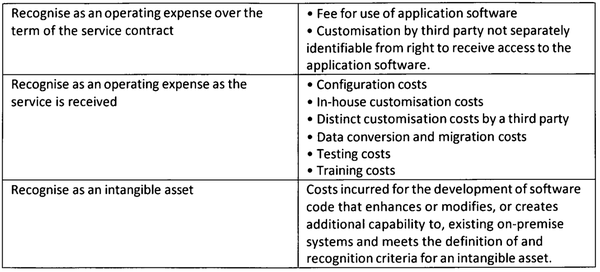
A SaaS setup can produce three treatments. Under full IFRS, sort vendor work, consultant fees and new code by who controls what and when each service arrives.
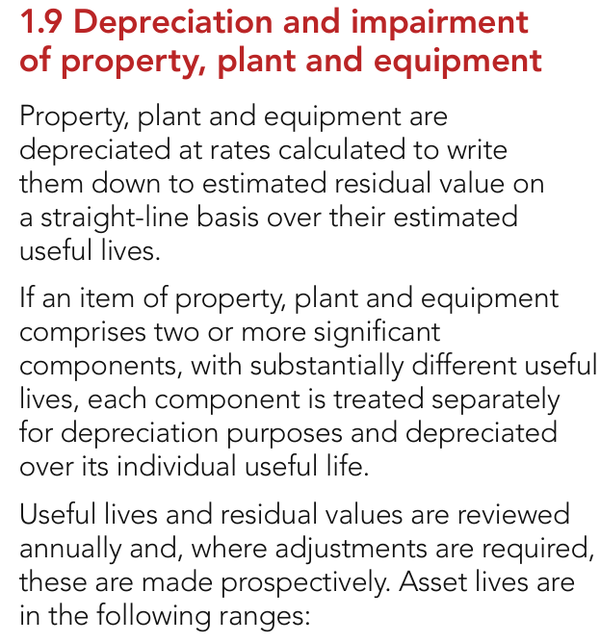
A machine's life is extended after two years. Under IAS 8, new evidence changes depreciation from now on; a past mistake made despite available evidence is restated.
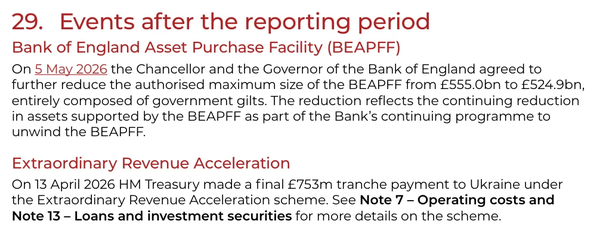
A May court settlement and an April fire reach the same 31 March accounts. Under UK-adopted IAS 10, one changes the figures and the other may need a note.
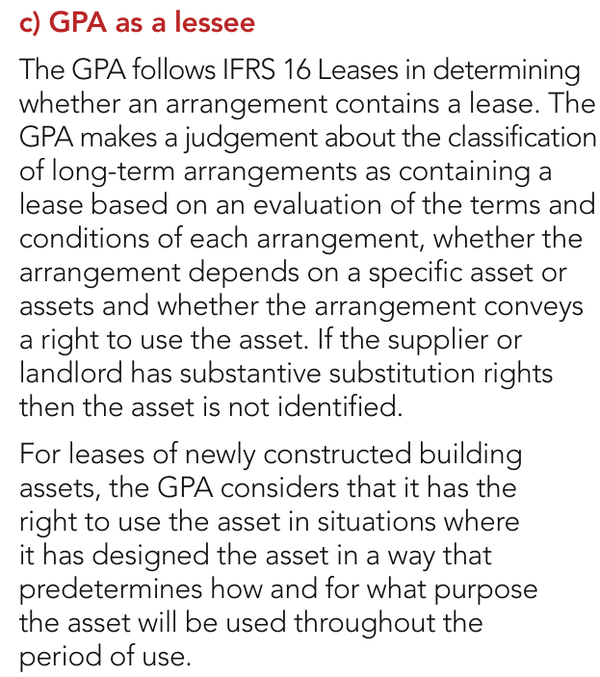
A contract called a service can still contain a lease under IFRS 16. Check the asset, substitution rights, benefits and decisions before building a schedule.
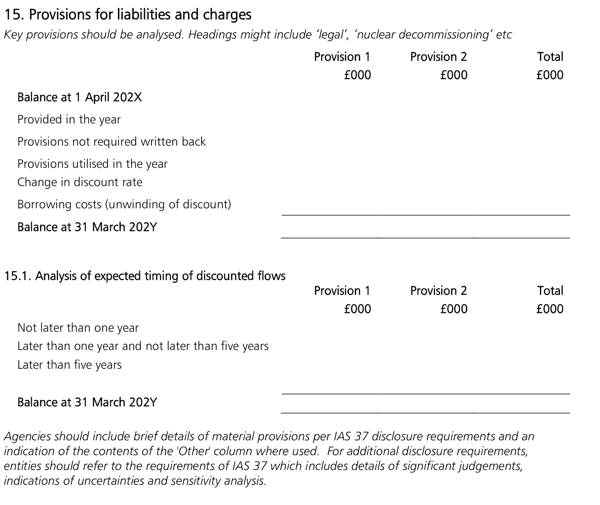
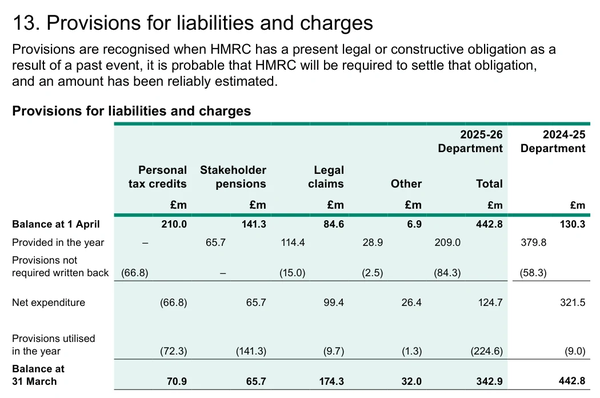
Four year-end items are labelled provisions. Under UK-adopted IAS 37, one is an accrual, one a provision, one a disclosure and one is none of these.