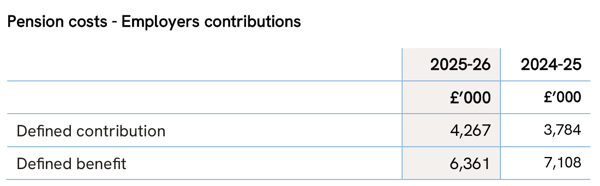
Defined contribution pensions: service cost before cash payment
Employer pension expense follows employees' service, while remittances clear the payable. Reconcile a genuine defined contribution plan across the year end.

Keep the books in order, plan for cash needs and understand reporting changes. Practical guides with worked examples and links to the evidence.
Employer pension expense follows employees' service, while remittances clear the payable. Reconcile a genuine defined contribution plan across the year end.
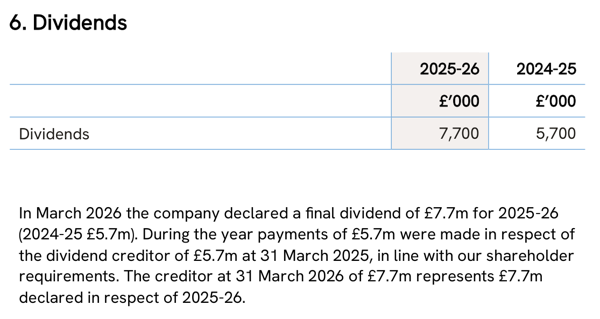
The profit year does not decide when an ordinary equity dividend becomes payable. Compare a binding December declaration with one first made in January.
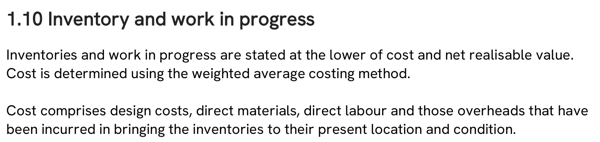
FIFO and weighted average divide the same inventory cost differently between sold and unsold units. Reconcile the cost before comparing the margin.
A qualifying origination fee changes a loan's carrying amount and effective interest expense. Follow a two-year loan from net proceeds to final repayment.
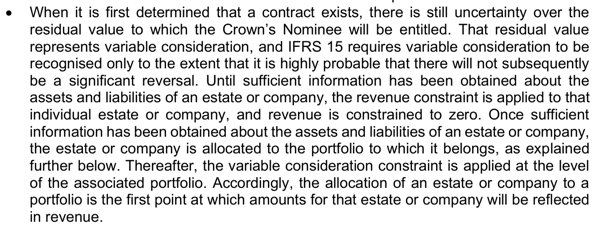
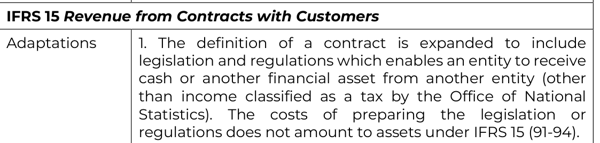
A bonus can be the most likely outcome and still be excluded from revenue. Separate the amount estimate, reversal constraint and progress calculation.
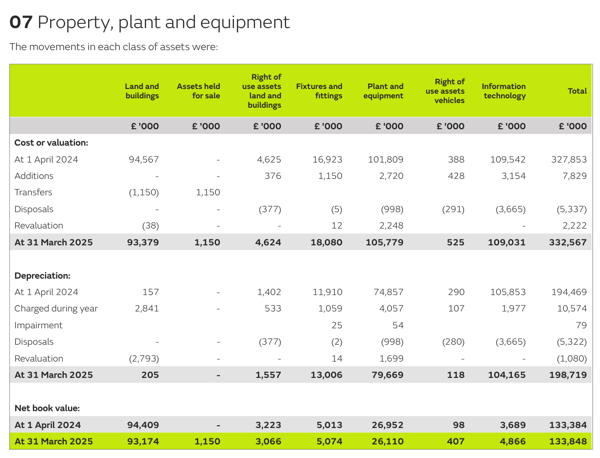
A machinery revaluation can create an OCI gain and a separate profit-or-loss expense. Class coverage and each asset's history decide the entries.
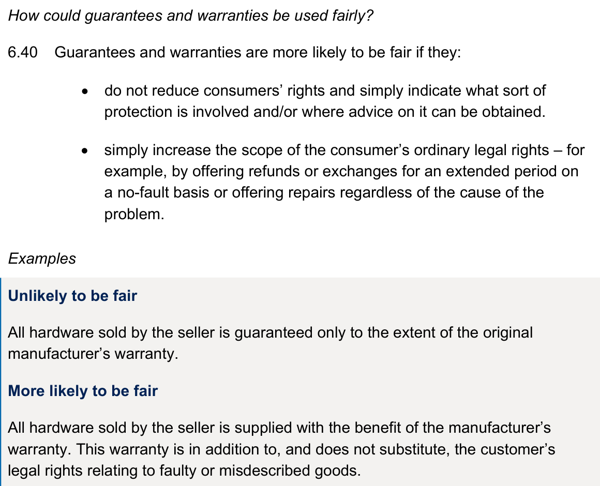
Read the warranty promise before posting the sale. Assurance and extra services follow different accounting, even when both are described as free cover.
A success-only commission can qualify as an asset while bid salaries remain expenses. Test incremental cost, recovery and the services the payment relates to.
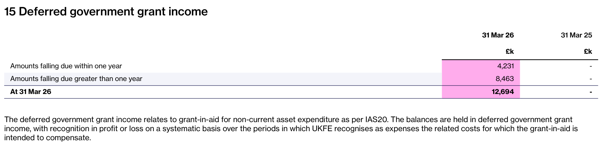
Receiving a grant does not decide when it reaches profit. Under IAS 20, a grant funding a new machine is released as it depreciates, using either of two presentations.
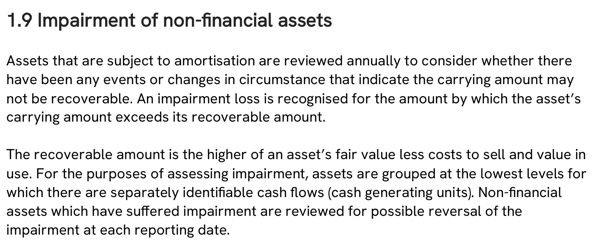
An idle machine can be overstated while it depreciates. Under IAS 36, an indicator triggers a test against the higher of fair value less disposal costs and value in use.
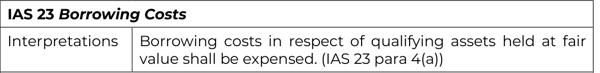
Under IAS 23, a project loan does not make every month of interest part of the asset. A hypothetical build shows when capitalisation starts, pauses and stops.
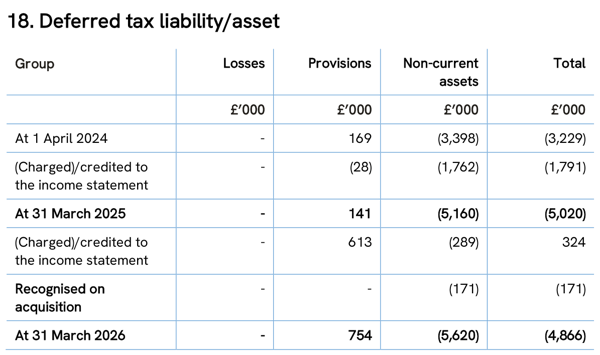
Under UK-adopted IFRS, deferred tax starts with the gap between carrying amount and tax base. A hypothetical machine shows the liability, the journal and the movement.